/
Land mortgages (UK)
Compare UK land mortgage brokers for plots, development land and agricultural finance. Planning permission, deposits and lender criteria explained. Get matched free with FCA-regulated brokers who list land experience. Directory only — not advice, no live rates.
Reviewed by David Sampson, Founder & Director
Can you get a mortgage on land?
Short answer: Yes, many buyers finance land or a plot with a mortgage in the UK — but availability depends on planning permission, deposit, land use and your wider circumstances. High-street residential products often do not fit; specialist panels are common.
Read our full Can you get a mortgage on land? guide for eligibility, planning, deposits and process detail.
Then compare FCA-regulated brokers who list land experience on our top land mortgage brokers list.
What is a land mortgage?
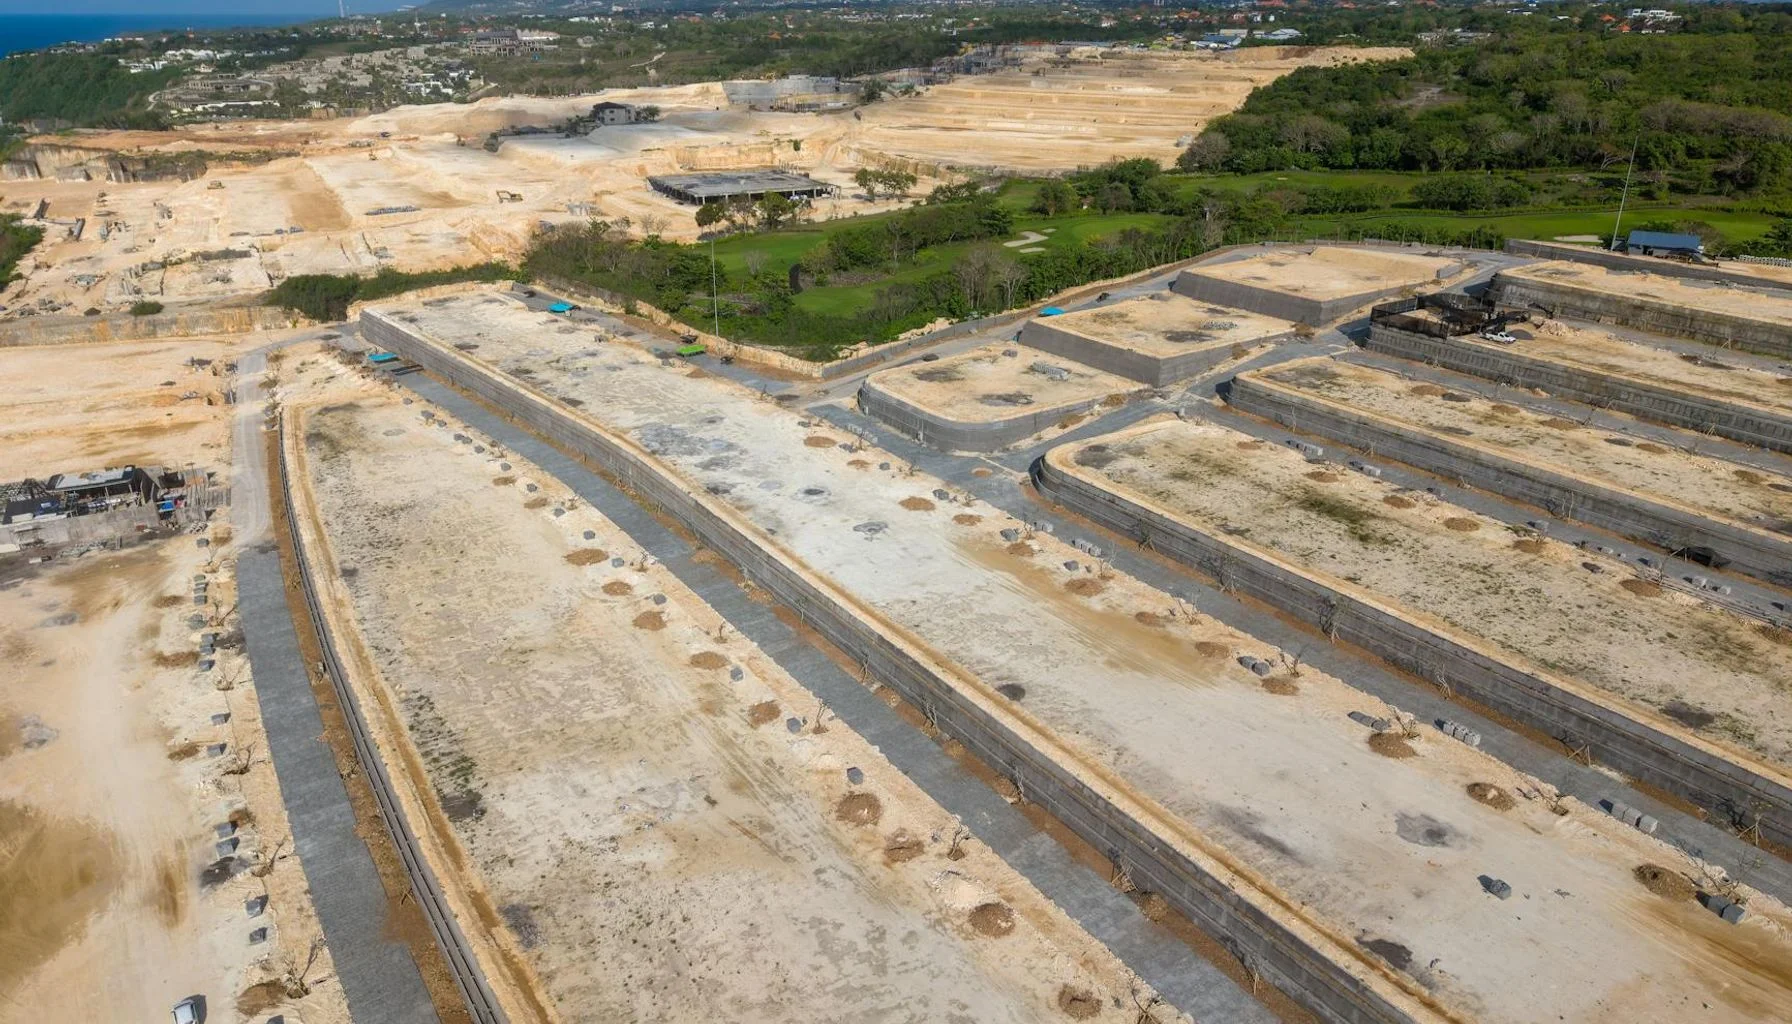
Land mortgages in the UK finance plot purchases for development, agricultural use, or investment. Deposits typically range from 30–50% depending on planning permission status, land type, and borrower experience. Planning permission — whether detailed, outline, or absent — is the strongest factor shaping lender appetite and pricing. Agricultural land is assessed on farming income potential, not planning. Mortgage118 is a broker directory: we help you compare brokers who list land experience, not quote rates ourselves. Commercial investment land is out of scope.
Land-only vs plot + build
Land-only mortgage: Finance to purchase the land or plot without a simultaneous construction package. You own the land outright and decide later whether to develop, sell, or hold.
Plot + build (self-build mortgage): Combined finance for land purchase and construction, released in stages as the build progresses. Often better for buyers who intend to build immediately.
| Factor | Land-only mortgage | Plot + build (self-build) |
|---|---|---|
| Scope | Land purchase only | Land + construction in one package |
| When it fits | You want to hold the land, develop later, or sell on | You intend to build your own home immediately |
| Release pattern | Lump sum at completion | Stage-release (foundations, walls, roof, etc.) |
| More info | Land hub | Self-build guide |
How land finance typically works (5 steps)
- Confirm your land details: Location, size, planning status (detailed/outline/none), intended use (development/agricultural/investment).
- Compare brokers with land experience: Browse top brokers. Brokers access specialist lender panels.
- Submit application + evidence: Financial documents, planning permission (if any), land survey, legal title. Lender commissions specialist land valuation.
- Underwriting: Lender assesses planning status, deposit, your financial position, exit strategy, and experience. Timeline varies by case complexity.
- Completion: Legal work (conveyancing, searches, title checks) and funds transfer. Timeline often longer than simple residential cases.
Mortgage118 is a broker directory. We do not approve applications, arrange mortgages, or quote live rates.
Planning permission — why it matters
A mortgage on land with planning permission is still a land mortgage. It is covered on this hub and on the yes/no guide. It does not have its own page.
Planning status is one of the facts lenders weigh when they look at a plot: how clear the use is, and how readily the land could be sold if needed. Detailed consent is usually easier to explain than outline consent. Land without planning permission is not a separate Mortgage118 product — the yes/no guide says that in one place.
Agricultural land sits outside this residential planning framework and is assessed on farming income potential. See our agricultural land mortgages guide.
Full detail: Land mortgage rates (UK) (no live quotes; market context only).
Deposits and LTV — market context
Land mortgages often require higher deposits than residential mortgages because lenders lend against a less liquid, more uncertain asset. Exact deposit requirements vary by:
- Planning permission status
- Land type (vacant, plot with planning, agricultural)
- Your financial position and experience
- Lender appetite and current criteria
General market context (not Mortgage118 advice or quotes): Plots with detailed planning permission may sit at the lower end of the deposit range; vacant land without planning often requires higher deposits. Agricultural land deposits vary by farm business strength and land grade.
Mortgage118 does not publish deposit bands or LTV figures as offers. Confirm requirements with an FCA-authorised broker for your specific case.
Plot mortgages and residential land finance
A plot mortgage and residential land finance are the same job as a land mortgage: secured finance to buy a residential plot in the UK. The same page covers a mortgage for land, a mortgage on land, a mortgage to buy land, and a land purchase mortgage.
Mortgage118 is a broker directory, not a lender. Compare brokers who list land experience, then use the spokes for the yes/no question, rates context, the calculator, and farm land.
Short-term land bridging, barn conversion, and development finance are different products. They are not part of this page. Farm land is the agricultural land mortgages spoke.
Next step: browse top land mortgage brokers · the yes/no guide on can you get a mortgage on land?
We do not offer loans, approve credit, or quote rates.
How does a land mortgage typically work?
1
Clarify your land or plot details
Before you startLocation, size, planning status (detailed/outline/none), intended use (development/agricultural/investment), and whether you have an architect or professional team
2
Research your options
1-2 daysVisit our land hub to understand deposits, timescales, and planning requirements. Use our land calculator to estimate costs. Review top land brokers or Get matched.
3
Compare brokers with land experience
30-60 minSpeak to FCA-regulated brokers who list land on their profile. They'll access specialist lender panels and explain your options.
4
Application via your broker
2-4 weeksSubmit financial documents, planning evidence, land survey, and legal title. Lender commissions specialist land valuation and underwrites your case.
5
Completion
3-6 weeksLegal work (conveyancing, searches, title checks) and funds transfer. Timeline varies by case complexity and lender.
What fees come with a land mortgage?
Arrangement Fee
Lender product fee
1–2%
of loan amount
Valuation Fee
Specialist land or rural surveyor
£1,000–£3,000+
higher than residential
Legal Fees
Conveyancing, searches, title
£1,500–£3,000+
complex cases cost more
Broker Fee
Advice and lender access
Varies
some brokers fee-free
Other Costs
Planning consultant, ecological reports, etc.
Variable
depends on case
Fees vary by lender. Advisers provide a breakdown before you proceed. Mortgage118 does not quote fees.
Resources
- FCA Register — Check a firm is authorised
- MoneyHelper — Free, impartial mortgage help
- GOV.UK — Business finance and support
FAQs
Related Articles
Practical guides and explainers from our blog — relevant to this mortgage type.
Also see
Calculators
Related mortgage types
Mortgage118 is a directory of FCA-authorised advisers, not a lender. We do not publish live rates. Confirm criteria with an authorised broker before you apply.
Important: Your home may be repossessed if you do not keep up repayments on your mortgage. Information on this page is for general guidance only and does not constitute financial advice.Always verify details directly and seek independent advice before making financial decisions.